
Saving money can feel impossible when groceries, housing, transportation, and everyday expenses consume most of your income. Even when you earn enough to cover your bills, unexpected costs can make it difficult to build financial security.
The solution isn’t necessarily to stop spending on everything you enjoy. It’s to understand where your money goes, decide what matters most, and create a system that makes saving easier.
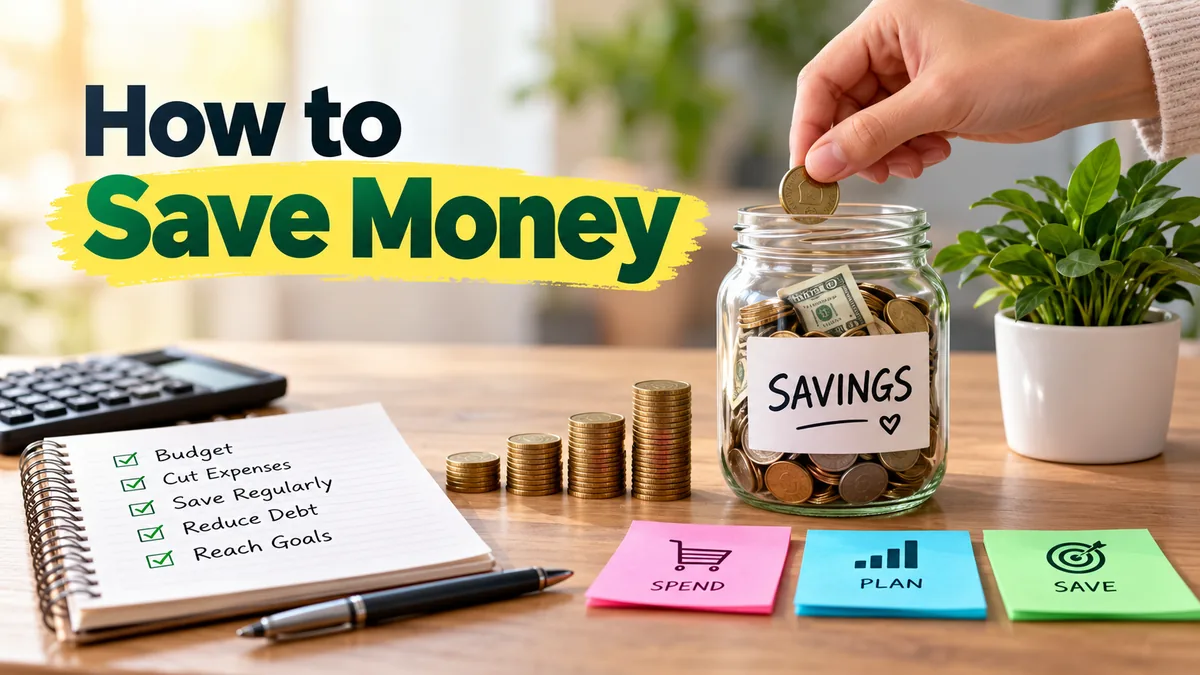
Learning how to save money starts with tracking your expenses, creating a realistic budget, reducing unnecessary costs, and setting aside a portion of your income regularly. Automating transfers, paying down expensive debt, and building an emergency fund can help you save consistently, even when your income is limited.
This guide explains practical strategies for saving money, avoiding common financial mistakes, and developing habits that support long-term financial stability.
1. How to Save Money by Creating a Realistic Budget
A budget gives you a clear picture of how much money comes in, where it goes, and how much you can realistically save.
Without one, it’s easy to underestimate small expenses or discover that you have nothing left at the end of the month.
Track your income and expenses
Start by reviewing your bank statements, credit card transactions, receipts, and digital payment history from the past two or three months.
Organize your spending into categories:
- Housing: Rent, mortgage payments, property taxes, and maintenance.
- Utilities: Electricity, water, gas, internet, and phone bills.
- Food: Groceries, restaurants, takeaway meals, and snacks.
- Transportation: Fuel, public transport, insurance, and vehicle repairs.
- Debt payments: Credit cards, personal loans, and other borrowing.
- Personal spending: Entertainment, shopping, hobbies, and subscriptions.
- Savings: Emergency funds, planned purchases, and long-term financial goals.
Distinguish fixed expenses, which remain relatively consistent, from variable expenses that change throughout the month.
Once you understand your spending patterns, you can identify categories where adjustments would make a meaningful difference.
Try the 50/30/20 budgeting rule
The 50/30/20 rule is a popular starting point for organizing after-tax income.
Example monthly take-home income: $3,000
Needs · 50%
$1,500
Wants · 30%
$900
Savings/debt · 20%
$600
Illustrative allocation, not a requirement. High housing costs or low income may make different percentages more realistic.
Under this framework, approximately 50% goes toward necessities, 30% toward discretionary spending, and 20% toward savings and extra debt repayments.
However, this method isn’t suitable for every household. If essential expenses consume 70% or 80% of your income, focus first on covering necessities and finding a sustainable amount to save.
Consider zero-based budgeting
With zero-based budgeting, every dollar of income is assigned a purpose before the month begins.
That doesn’t mean spending everything. Money allocated to savings counts as part of the plan.
For example, someone earning $2,500 might assign $1,600 to necessities, $400 to discretionary expenses, $300 to savings, and $200 to debt repayment.
The goal is to avoid leaving money unaccounted for.
2. How to Save Money on Everyday Expenses
Daily spending habits often offer the easiest opportunities to reduce expenses without making major lifestyle changes.
Reduce grocery spending without sacrificing nutrition
Food is an essential expense, but poor planning can make grocery bills unnecessarily expensive.
Try these strategies:
- Plan meals around ingredients you already own.
- Create a shopping list and follow it.
- Compare unit prices rather than package prices.
- Buy store-brand products when quality is comparable.
- Choose seasonal produce and reasonably priced protein sources.
- Freeze leftovers before they spoil.
- Avoid shopping while hungry if it encourages impulse purchases.
Buying in bulk can reduce unit costs, but only when you’ll use the products before they expire.
For example, purchasing a large package of rice may make sense for a household that regularly consumes it. Buying excessive fresh produce that eventually spoils can have the opposite effect.
Spend less on dining out
Restaurant meals, takeaway orders, and delivery fees can add up quickly.
Suppose you spend $15 on lunch four times per week. That’s approximately $240 over four weeks.
Preparing lunch at home for $5 per meal would reduce that spending to around $80, creating a potential monthly saving of $160.
You don’t need to eliminate restaurants completely. Setting a dining-out allowance can help you enjoy occasional meals without undermining your savings goals.
Cut electricity and utility bills
Reducing energy consumption can lower household expenses, although actual savings depend on local utility rates, climate, and your home’s efficiency.
Useful actions include switching off unused lighting, using LED bulbs, sealing air leaks, washing full laundry loads, and adjusting heating or cooling settings when practical.
Review your electricity bill to understand whether you’re charged different rates during peak and off-peak hours.
For larger improvements, compare the upfront cost of efficient appliances or insulation against their expected long-term savings before investing.
Review subscriptions and memberships
Streaming platforms, mobile applications, cloud storage, gaming services, and gym memberships often renew automatically.
Review recurring charges every month or quarter.
Ask yourself whether you regularly use each service, whether a cheaper plan would work, and whether multiple subscriptions provide similar benefits.
Canceling three unused subscriptions costing $12 each would save $36 monthly, or $432 annually.
3. Build an Emergency Fund and Automate Savings
An emergency fund protects your finances when something unexpected happens.
Medical expenses, urgent home repairs, job loss, and vehicle breakdowns can otherwise force you to rely on expensive borrowing.
How much should you save for emergencies?
A common long-term guideline is to build enough accessible savings to cover three to six months of essential living expenses.
For someone whose essential monthly expenses total $2,000, that would mean:
| Emergency fund target | Amount |
|---|---|
| One month | $2,000 |
| Three months | $6,000 |
| Six months | $12,000 |
Your ideal amount depends on job stability, dependents, healthcare costs, insurance coverage, and other financial risks.
If these figures seem overwhelming, begin with a smaller milestone such as $500 or $1,000, then gradually increase your balance.
Pay yourself first
The pay-yourself-first method involves transferring money into savings before allocating the remainder to discretionary spending.
Instead of saving whatever remains at the end of the month, decide on a manageable amount and treat it as a planned financial commitment.
For example, transferring $50 every payday can be easier than trying to find $100 after a month of spending.
Automate your savings
Automatic transfers reduce the need to make repeated saving decisions.
You can arrange for a fixed amount to move from your checking account into a separate savings account shortly after receiving your salary.
Some banks and financial applications also offer round-up features, which transfer small amounts based on debit card purchases.
These tools can support consistent saving, but check for account fees, transfer restrictions, and overdraft risks.
Choose a suitable place for your savings
Emergency savings should generally be kept somewhere safe, accessible, and separate from everyday spending.
In the United States, an FDIC-insured bank savings account or an eligible NCUA-insured credit union account may provide deposit protection within applicable limits.
A high-yield savings account may offer a better interest rate than a traditional savings account, although rates can change.
Avoid exposing money needed for immediate emergencies to significant stock market volatility.
4. How to Save Money When You Have a Low Income
Saving on a limited income requires a different approach from saving when you have substantial disposable income.
When necessities consume most of your earnings, even a small unexpected bill can disrupt your finances.
Start with an amount you can maintain
Saving $5 or $10 regularly is still useful if it doesn’t interfere with essential expenses.
For example:
| Weekly savings | Savings over 52 weeks |
|---|---|
| $5 | $260 |
| $10 | $520 |
| $20 | $1,040 |
| $50 | $2,600 |
These figures exclude interest and assume every weekly contribution is made.
Consistency matters more than beginning with an impressive amount.
Prioritize essential spending
When income is tight, organize spending around immediate needs such as housing, food, utilities, transportation to work, and necessary medical care.
Then review flexible expenses.
Reducing an entertainment subscription may help, but it won’t solve a budget where rent and essential bills already exceed income.
In that situation, increasing income, negotiating payment arrangements, checking eligibility for assistance programs, or seeking reputable financial counseling may be more effective.
Explore ways to increase income
There is a limit to how much you can cut from a budget.
Depending on your skills and circumstances, additional income might come from freelance work, tutoring, selling unused belongings, part-time employment, or requesting additional hours at your current job.
Consider taxes, transportation, childcare, equipment, and other expenses before assuming a side job will be profitable.
Directing part of any additional net income into savings can accelerate progress without requiring further cuts to essential spending.
Use irregular income carefully
Freelancers, contractors, and seasonal workers often experience unpredictable earnings.
A practical approach is to build a budget around a conservative income estimate and save part of higher-income months to cover leaner periods.
Keeping a separate reserve for taxes and business expenses can also prevent unexpected financial pressure.
5. Reduce Debt and Avoid Expensive Financial Mistakes
Debt repayment and saving are closely connected.
High-interest borrowing can consume money that would otherwise support your financial goals.
Understand how interest affects your budget
Suppose you carry a $3,000 credit card balance with a 24% annual percentage rate.
At an approximate monthly rate of 2%, the first month’s interest would be around $60 if the balance remained unchanged throughout the billing period. Actual interest depends on the card’s calculation method and payment activity.
That cost can make saving difficult, especially when only minimum payments are made.
Compare debt repayment methods
Two widely used approaches are the debt avalanche and debt snowball methods.
| Method | How it works | Main advantage |
|---|---|---|
| Debt avalanche | Pay extra toward the highest-interest debt first | Generally minimizes total interest |
| Debt snowball | Pay extra toward the smallest balance first | Provides quicker balance-payoff milestones |
With either approach, continue making required payments on other debts.
The avalanche method is usually mathematically more efficient, while the snowball method may be easier to maintain for people motivated by visible progress.
Should you save money or pay off debt first?
The answer depends on the type of debt, its interest rate, and your financial circumstances.
A reasonable approach is to maintain a small emergency buffer while directing extra funds toward high-interest debt.
Otherwise, an unexpected expense could force you to borrow again.
Also consider employer retirement matching contributions, minimum payment obligations, and any penalties or restrictions associated with your accounts.
Avoid impulse purchases and lifestyle inflation
Impulse spending can gradually undermine a carefully planned budget.
Before making a nonessential purchase, consider waiting 24 hours. For larger purchases, a longer waiting period may be appropriate.
Ask whether you genuinely need the item, already own something similar, and can afford it without using money intended for necessities or savings.
Lifestyle inflation presents another challenge. When earnings increase, spending often rises alongside them.
Saving a portion of each salary increase can improve financial security while still allowing some lifestyle improvements.
6. Save Money on Housing, Transportation, and Major Bills
Small savings are useful, but reducing large recurring expenses can have an even greater impact.
Housing, transportation, and insurance often account for a significant portion of household spending.
Review your housing costs
If rent or mortgage payments consume an unusually large share of your income, consider whether your current housing arrangement remains affordable.
Possible options include negotiating a lease renewal, sharing accommodation, moving to a less expensive neighborhood, or reducing unnecessary household services.
Moving isn’t automatically cheaper. Security deposits, transportation costs, moving fees, and changes in commuting expenses should all be included in the calculation.
Homeowners considering refinancing should compare interest rates, closing costs, loan terms, and the total cost of borrowing.
Reduce transportation expenses
Transportation costs extend beyond fuel or monthly car payments.
They can include insurance, registration, maintenance, parking, tolls, depreciation, and repairs.
Depending on your location, combining errands, carpooling, using public transportation, or walking short distances may reduce expenses.
Regular vehicle maintenance can also help prevent some expensive repairs.
Before replacing your vehicle with a more fuel-efficient model, compare the potential savings against the purchase price and financing costs.
Compare insurance coverage
Insurance is necessary financial protection, but paying for unsuitable or duplicate coverage can strain your budget.
Review policies periodically and compare equivalent coverage from reputable providers.
A higher deductible may reduce premiums, but it also increases what you must pay when making a claim.
Choose a deductible you could reasonably afford during an emergency.
Avoid reducing essential protection simply to achieve a lower monthly bill.
Negotiate recurring bills
Internet providers, mobile carriers, and some service companies may offer alternative plans or promotional rates.
Review your actual usage before contacting them.
For example, if you’re paying for more mobile data than you regularly consume, switching to a smaller plan could provide ongoing savings.
Even a $25 monthly reduction in recurring bills represents $300 over a year.
7. Set Savings Goals and Build Long-Term Financial Habits
Saving becomes easier when your money has a specific purpose.
A vague goal such as “save more” provides little guidance. A measurable target creates a clearer path.
Create specific savings goals
Start by identifying what you’re saving for, how much you need, and when you want to reach your target.
Common goals include building an emergency fund, buying a vehicle, paying for education, preparing for a home deposit, or funding retirement.
Separate goals into short-term, medium-term, and long-term categories.
Money needed within the next year generally requires a different approach from money intended for retirement decades away.
Calculate how much you need to save
Use this basic formula:
\[ \text{Monthly Savings}=\frac{\text{Target Amount}-\text{Current Savings}}{\text{Months Remaining}} \]
For example, if you want to save $5,000 in 12 months and currently have $800, you’ll need to save $350 per month, excluding interest.
You can use the calculator below to estimate your own target.
Savings goal calculator
Target amount ($)Already saved ($)
Time to reach your goal
12 months
Required monthly savings
$350.00
Assumes no interest, fees, or withdrawals.
If the required monthly amount is unrealistic, extend your timeline, reduce the target, or look for ways to increase available income.
Use sinking funds for predictable expenses
An emergency fund should cover unexpected financial problems.
A sinking fund serves a different purpose: preparing for expenses you know are coming.
Examples include annual insurance premiums, school fees, holiday gifts, vehicle servicing, and property taxes.
Suppose your annual car insurance premium is $1,200. Saving $100 each month means you can prepare for that payment without disrupting your regular budget.
Separating these predictable expenses from emergency savings helps protect your financial safety net.
Understand saving versus investing
Saving and investing both support financial goals, but they involve different levels of risk.
Savings accounts generally prioritize accessibility and preservation of money, while investments such as stocks, bonds, mutual funds, and exchange-traded funds may provide long-term growth but can lose value.
Compound interest or compounded investment returns can help money grow over time, although investment returns are not guaranteed.
For example, contributing $100 monthly for 20 years would total $24,000 before earnings.
At a hypothetical 5% annual return compounded monthly, those contributions could grow to approximately $41,100 before taxes and fees. Actual results will vary.
Retirement accounts such as 401(k)s and Individual Retirement Accounts (IRAs) may provide tax advantages in the United States, depending on eligibility and applicable rules.
For emergency money or short-term purchases, avoiding substantial market risk is generally more important than pursuing higher potential returns.
Review your progress regularly
A savings plan should change when your financial circumstances change.
Review your budget at least once a month to compare planned spending with actual expenses.
If you receive a salary increase, bonus, tax refund, or financial gift, consider directing a portion toward your savings goals.
If unexpected expenses reduce your savings, adjust your contributions rather than abandoning the plan.
The Consumer Financial Protection Bureau recommends establishing a savings habit, setting specific goals, and monitoring progress regularly.

Consumer Financial Protection Bureau
8. Common Money-Saving Mistakes to Avoid
Even people who budget carefully can make decisions that slow their financial progress.
Understanding these mistakes can help you protect the money you’ve worked to save.
Buying unnecessary items because they’re discounted
A 40% discount doesn’t automatically make a purchase worthwhile.
If an item normally costs $100 and is discounted to $60, you’re spending $60—not saving $40—unless you genuinely needed the product and would otherwise have purchased it.
Compare the final cost with your budget rather than focusing only on the advertised discount.
Ignoring irregular expenses
Annual subscriptions, school expenses, holiday spending, and vehicle maintenance can make a monthly budget appear healthier than it actually is.
Review expenses from the previous year and divide predictable annual costs into monthly savings amounts.
This creates a more accurate picture of your disposable income.
Saving too aggressively
An unrealistic savings target can lead to missed bill payments, repeated withdrawals, or reliance on credit cards.
Saving 30% of your income isn’t beneficial if it forces you to borrow money at high interest to purchase necessities.
Choose a sustainable contribution that supports your financial stability.
Keeping all savings in one account
Combining emergency money, holiday savings, and everyday spending can make it difficult to track progress.
Separate accounts or clearly labeled savings categories can help distinguish money available for emergencies from funds allocated to planned purchases.
Overlooking banking fees
Account maintenance charges, overdraft fees, ATM charges, and transfer fees can gradually reduce your savings.
Review account terms and look for suitable low-fee alternatives.
For U.S. consumers, the FDIC provides information about eligible insured deposit accounts and coverage limits. The standard coverage is $250,000 per depositor, per insured bank, per ownership category.
FDIC
Depending entirely on motivation
Motivation changes, especially when financial goals take months or years to achieve.
Automatic transfers, written budgets, spending alerts, and scheduled financial reviews can reduce dependence on willpower.
The most effective system is usually one that requires relatively little effort to maintain.
9. A Simple 30-Day Plan to Start Saving Money
You don’t need to overhaul your finances overnight.
A structured first month can help you establish habits and identify opportunities for improvement.
| Timeframe | Action | Main objective |
|---|---|---|
| Days 1–7 | Review income, bills, and transactions | Understand spending |
| Days 8–14 | Build a budget and reduce unnecessary expenses | Free up money |
| Days 15–21 | Establish savings goals and automate transfers | Create consistency |
| Days 22–30 | Review results and adjust your plan | Maintain progress |
Week 1: Understand your financial situation
Collect recent bank statements, credit card statements, bills, and income records.
Calculate your total monthly income and essential expenses.
Identify subscriptions, discretionary purchases, and irregular costs.
Don’t immediately eliminate every optional expense. First, understand which changes could make the greatest difference.
Week 2: Reduce avoidable spending
Choose two or three realistic adjustments.
You might prepare lunch at home more often, cancel an unused subscription, compare mobile plans, or reduce unnecessary shopping.
Estimate the monthly savings from each change.
Focus on adjustments you can maintain without making everyday life unnecessarily difficult.
Week 3: Create your savings system
Set a specific savings target and select a suitable account.
Schedule a recurring transfer that aligns with your payday.
If your income is irregular, consider saving a fixed percentage of each payment rather than a fixed monthly amount.
Start with an amount that leaves sufficient money for essential bills.
Week 4: Measure your results
Compare your actual spending against your budget.
Calculate how much you saved and identify which changes were easiest to maintain.
If you saved less than expected, investigate why.
Your budget may need more room for groceries, transportation, healthcare, or other necessary expenses.
Use what you learn to create a more realistic plan for the following month.
10. How Much Money Should You Save Each Month?
There is no universal savings percentage that works for everyone.
A commonly discussed goal is saving around 20% of after-tax income, including certain extra debt repayments under the 50/30/20 framework.
However, your appropriate savings rate depends on income, household responsibilities, debt, housing costs, and financial goals.
Consider the following examples:
| Monthly take-home income | 5% savings | 10% savings | 20% savings |
|---|---|---|---|
| $1,500 | $75 | $150 | $300 |
| $2,500 | $125 | $250 | $500 |
| $4,000 | $200 | $400 | $800 |
| $6,000 | $300 | $600 | $1,200 |
These percentages are examples, not mandatory targets.
Someone earning $1,500 with substantial essential expenses may struggle to save 5%, while a person with lower fixed costs may comfortably save more than 20%.
A better question is: How much can I save consistently without compromising essential needs or accumulating expensive debt?
Once you establish that amount, look for opportunities to increase it gradually.
11. How to Save Money Consistently for Years
Long-term financial stability comes from maintaining useful habits through changing circumstances.
Your savings strategy at age 20 may look different from your approach when supporting a family, purchasing a home, or preparing for retirement.
Make saving part of your routine
Treat saving as a regular financial activity rather than an occasional decision.
Schedule transfers, review balances, and update your goals when necessary.
Australia’s government-backed Moneysmart guidance, updated in September 2026, emphasizes clear goals, budgeting, automatic transfers, and progress tracking as practical ways to develop lasting saving habits.
Moneysmart
Increase savings when expenses decrease
When you finish repaying a loan, cancel an unnecessary service, or reduce another recurring expense, consider redirecting some of the freed-up money into savings.
For example, after completing a $200 monthly car loan payment, transferring that amount into savings could build $2,400 over the following year, excluding interest.
This approach allows savings to grow without requiring a new reduction in your existing lifestyle.
Protect your progress
Maintaining appropriate insurance, avoiding high-interest debt, monitoring account activity, and preparing for irregular expenses can help protect your financial progress.
Review your financial goals after major life changes such as marriage, relocation, childbirth, job changes, or retirement.
A flexible savings strategy is more likely to remain useful than one built around rigid rules.
Conclusion: Start Small and Make Saving a Habit
Learning how to save money doesn’t require a perfect income, an extremely restrictive budget, or complicated financial tools.
It begins with understanding your expenses, identifying realistic opportunities to spend less, and regularly setting aside money for future needs.
Start by tracking your spending, choosing one manageable savings goal, and automating a contribution you can afford. Build a small emergency fund, address expensive debt, and review your progress each month.
Small financial improvements may seem insignificant at first, but consistent contributions and reduced recurring expenses can produce meaningful results over time.
The most effective savings plan isn’t necessarily the one that promises the largest amount. It’s the one you can maintain while meeting your needs and improving your financial security.
